innoscripta
innoscripta

Austria

Make your R&D Tax Credit Audit-proof

Austria's 14% R&D premium requires no prior approval, but the tax office checks everything afterwards. We help Austrian innovation teams build evidence that survives every Betriebsprüfung, captured in your workflow, not reconstructed at year-end.

Lukas Hehle

Lukas Hehle

Managing Director

R&D tax credit export in one click

R&D tax credit export in one click

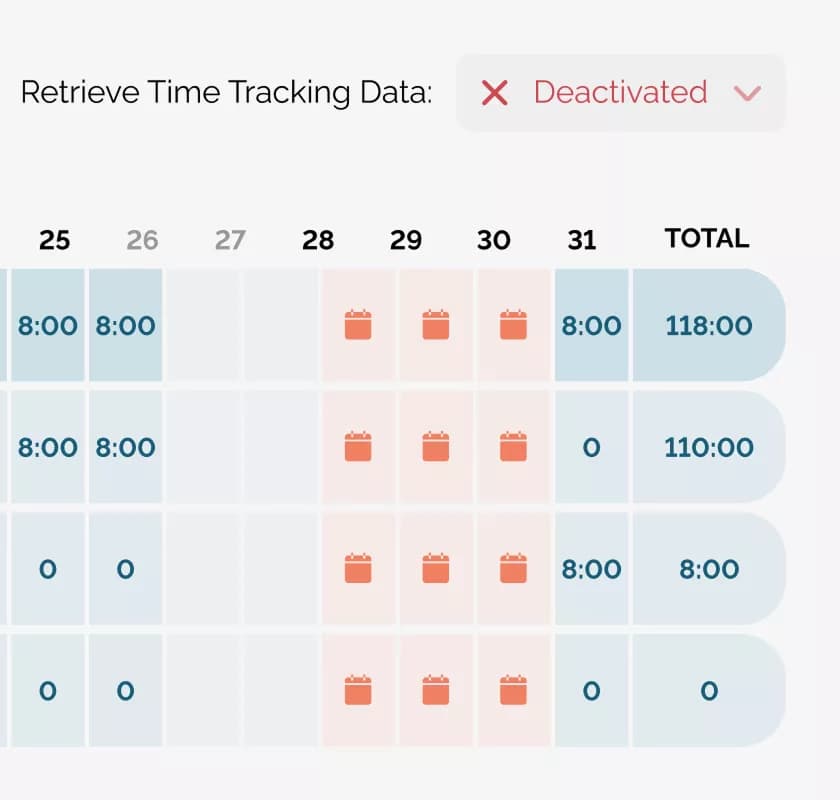
Time records according to BAO-compliance

Time records according to BAO-compliance

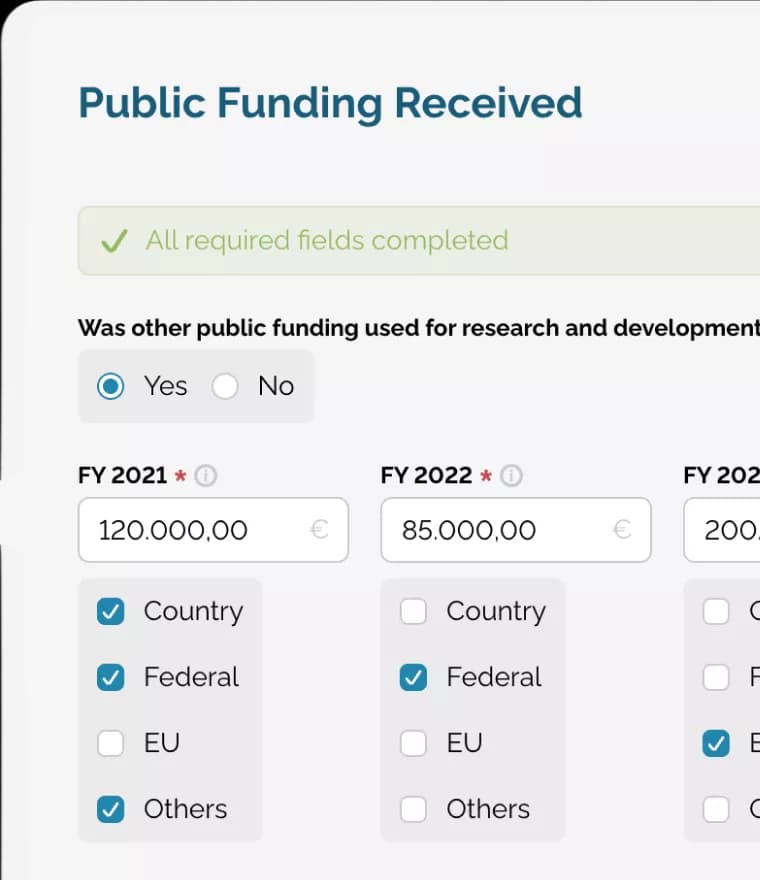
FFG grant auto-tracked

FFG grant auto-tracked

Atlas CopcoDaikinJack WolfskinWellaKuehne NagelLeica Biosystems logoSsi Schaefer

Forschungsprämie (§ 108c EStG)

Max cashback14%
Contract research: max. €1M.
Assessment basisNo annual limit
Unlimited for in-house R&D.
Filing deadlineWith annual tax return
Filed with annual tax return.
Who can applyAll company sizes
Startups to enterprises.
Retroactive claimsYes
Via amended tax returns.
Eligible costsPersonnel, materials, external R&D, depreciation
+ 25% overhead on eligible costs.

For every €1M in R&D spend, see an illustrative estimate of €140K

Use the calculator to get an estimate on your Funding potential. Actual eligibility and outcomes depend on your circumstances and the applicable rules.

The tax office checks after, not before Are you ready?

Risk
Unprepared for tax audits

The tax office can request an expert's opinion anytime. No records means no defense.

Grant deduction errors

Public grants must be offset from the assessment basis. Manual tracking routinely fails.

Internal & external R&D costs mixed up

Wrong classifications trigger full reclaim of the tax credits.

BAO burden of proof on you

No prior approval needed. Every claimed Euro must be proven in a retroactive audit.
Clusterix
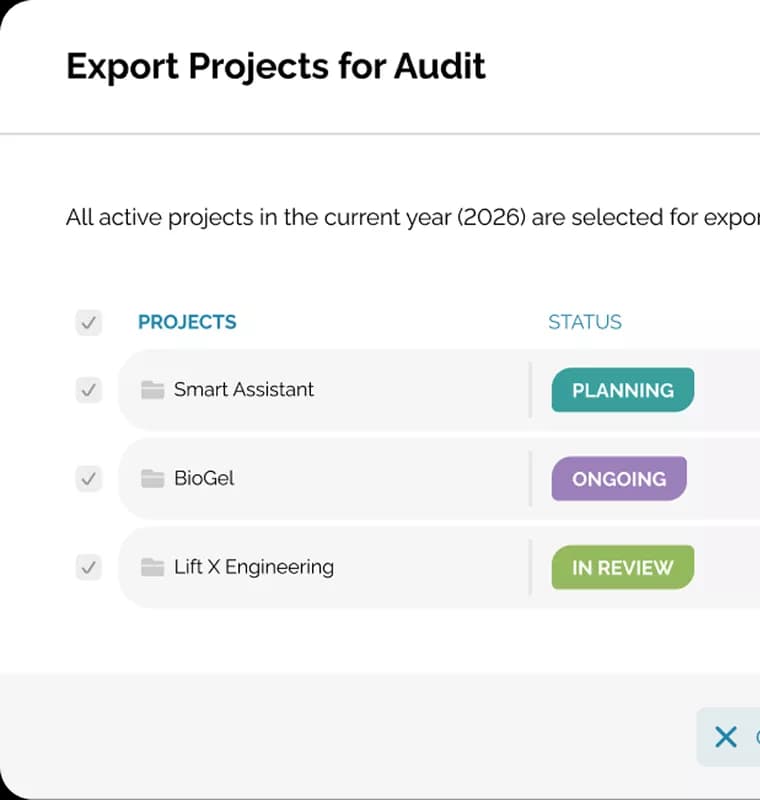
Audit-proof documentation

Project records available on demand. No scramble when the expert opinion is requested.

Automated grant deduction

FFG, aws, and EU grants offset from the assessment basis automatically.

Internal & external R&D costs separated

In-house and contract R&D classified and calculated correctly.

BAO-compliant documentation

Timestamped, version-controlled records, compliant with Austrian tax and accounting regulations (BAO and UGB)

See how Clusterix makes you audit-proof

One workflow from project plan to audit-proof evidence. No special sprints, no year-end scramble.
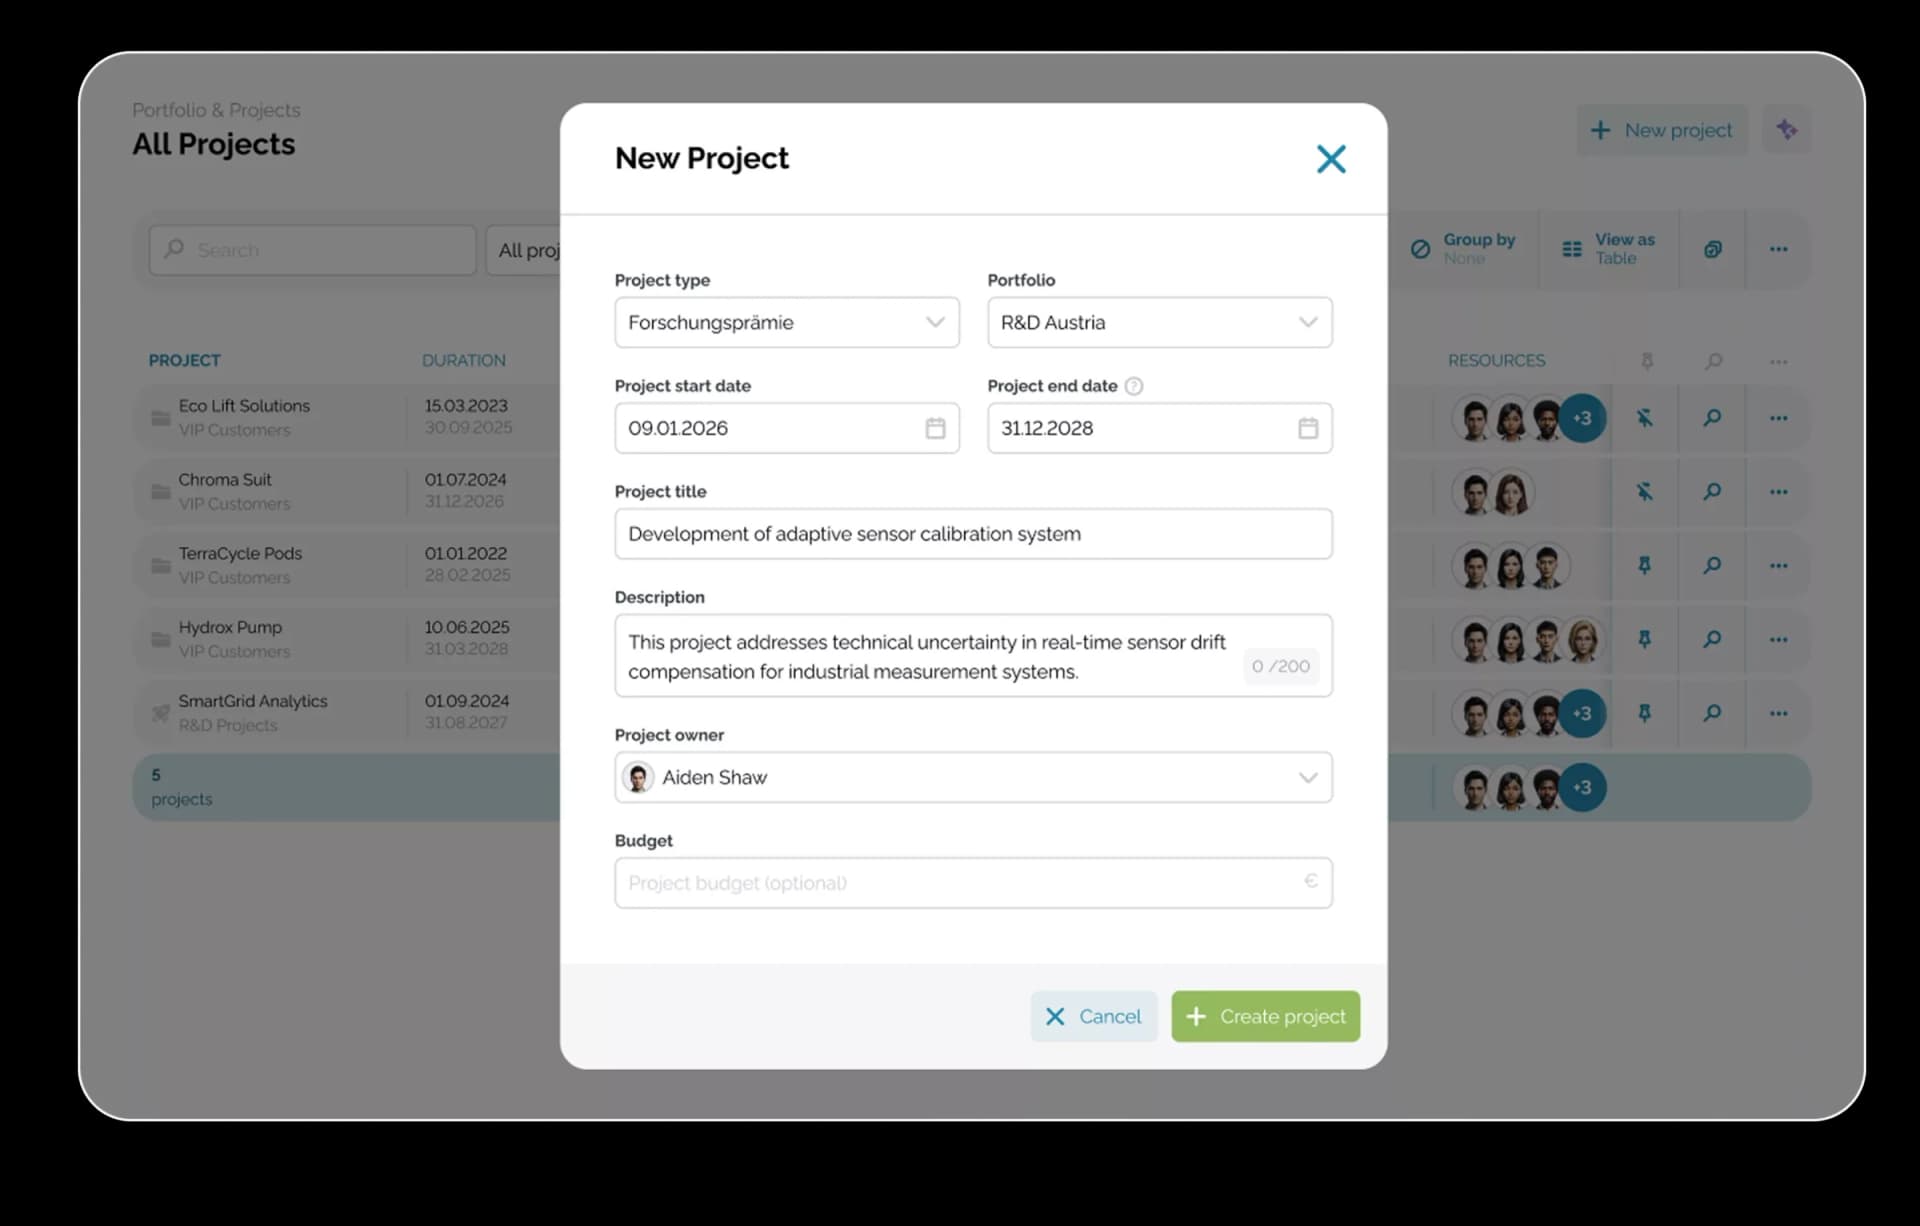
Project setup with R&D qualification check
Leica Biosystems Nussloch GmbH
“For me, it was the perfect combination of technology and personal consulting. The application process was much easier and faster than I had expected. The collaboration with innoscripta was efficient and always personal. (…) It was a true partnership.”
Paul Hertfelder, Senior Manager R&DLeica Biosystems Nussloch GmbH
read story

Frequently asked questions

Common questions about the Forschungsprämie.

The Forschungsprämie (§ 108c EStG) is a direct 14% cash premium on eligible R&D expenditures in Austria. Unlike tax deductions, it is paid out regardless of whether your company is profitable. It covers in-house R&D (Eigenforschung) and contract R&D (Auftragsforschung) and is claimed as part of your corporate tax return (KöSt-Erklärung).
No prior approval is required. However, the Finanzamt may request a Gutachten (expert opinion) from the FFG as part of a subsequent review. This is why having Frascati-aligned documentation is critical: the FFG assesses whether your activities genuinely qualify as R&D under OECD definitions.
Any non-repayable public funding, including FFG Basisprogramme grants, aws subsidies, and EU Horizon Europe contributions, must be deducted from the eligible R&D expenditure base before calculating the 14% premium. Failure to do this correctly is a common trigger for Finanzamt adjustments and penalties.
Eligible costs include personnel expenses for R&D staff, materials and supplies costs, depreciation of R&D equipment, and payments to third-party R&D contractors. Activities must qualify under the OECD Frascati Manual as basic research, applied research, or experimental development.
The Finanzamt expects detailed project descriptions demonstrating R&D character, time records linking personnel to specific R&D activities, cost breakdowns by project, and evidence that public grants have been correctly offset. Under BAO provisions, the burden of proof is on the claiming company, and documentation must have been created contemporaneously, not assembled after the fact.
Retroactive claims are possible for up to 4 years via amended tax returns. This means eligible R&D expenditure from previous fiscal years can still be recovered, provided sufficient documentation exists for those periods.

Ready to make your tax credit audit-proof?

Book a call with our Austria team and see how Clusterix captures tax credit evidence in real time.

Lukas Hehle

Lukas Hehle

Managing Director
innoscripta

The data layer for R&D, a continuous, verifiable record of the work your teams actually do, captured at source. Publicly listed, ISO 27001-certified, in 20+ countries.

innoscripta provides software solutions, documentation support, and general information on R&D funding. Our services do not include individual tax, legal, or financial advice.

Eligibility, funding rates, and potential outcomes depend on the applicable laws and regulations as well as the specific circumstances of the company and the respective project. Before submitting an application, we therefore recommend seeking qualified tax, legal, or financial advice where appropriate.

For further information, please refer to our information notice.


Copyright © 2026 - innoscripta SE

Handelskai 94/96, Vienna, Austria

+43 1 928 800 704

info@innoscripta.com

Make your R&D tax credit audit-proof in Austria | innoscripta